
Key Takeaways:
- Readers cost $0 to $200, terminals cost $150 to $450, and POS systems with built-in payments cost $150 to $1,900. Processing fees cost more over time.
- Square, Clover, and PayPal charge about 2.3% to 2.6% plus 9 to 15 cents per in-person sale. Helcim adds a smaller markup to the wholesale card fee, which often costs less for stores with steady, higher card sales.
- Leases run 36 to 48 months, are usually non-cancelable, and can cost several times the price of the machine.
- Statement, PCI, chargeback, and early termination fees add up, and a terminal must work with your processor.
A credit card machine costs $0 to $450 for most readers and terminals, and up to $1,900 for a POS system with built-in payments. The bigger cost is processing fees, which take a percentage of every sale.
This guide lists 2027 prices by machine type, compares processors, and explains leases and extra fees. It also covers a card network settlement that may lower some credit card fees.
Credit Card Machine Costs by Type
Pick the machine type by how you sell. A store with a fixed checkout fits a countertop terminal or POS system, a restaurant fits a portable terminal, and a food truck fits a mobile reader. Businesses that take orders by phone or online use a virtual terminal for card-not-present transactions.
| Type | Examples | Upfront cost | Best for | Watch for |
|---|---|---|---|---|
| Mobile card reader | Square Reader, PayPal Card Reader, Clover Go, Helcim Card Reader | $0–$200 | Food trucks, pop-ups, low startup cost | Needs a phone or tablet and an internet connection |
| Countertop terminal | Dejavoo QD4, Dejavoo Z11, PAX A80, PAX S300 | $150–$450 | Fixed checkout with steady volume | Not portable; must work with your processor |
| Portable terminal | PayPal Terminal, Square Terminal, Helcim Smart Terminal, Clover Flex | $199–$749 | Restaurants, cafes, tableside or large floor | Battery life; higher cost |
| POS system with built-in payments | Square Stand, Clover Mini, Square Register, Clover Station Duo | $150–$1,900 | Retail and restaurants that need inventory and reporting | Higher cost and training; often tied to one processor |
| Virtual terminal | Helcim, Square Virtual Terminal, Clover payments-only plan | $0–$30 per month | Phone and mail orders, remote sales | Higher fees and fraud risk; no in-person payments |
Machine prices only. Processing fees and software plans cost extra.
These prices cover the machine only. Your processor’s fees and any monthly software plan come on top, and full retail POS setups with several lanes can pass $10,000.
Built-In POS Terminals vs. Third-Party Processing Hardware
Built-in terminals come from the same company that provides your POS software and your payment processing, as with Square or Clover. Setup is simple, but you are tied to that company’s processing rates, which add up fast for higher-volume stores.
Third-party hardware pairs your POS with a separate terminal and a processor you choose, so you can negotiate rates or switch processors without replacing the POS. KORONA POS is processing agnostic, works with any credit card processor, and offers preconfigured credit card machines backed by emergency support.
| Option | Pros | Cons |
|---|---|---|
| Built-in POS terminal |
|
|
| Third-party processing hardware |
|
|
Processor Pricing Compared
Your processor sets most of your cost, so compare processors before you pick a machine. Flat-rate providers charge one rate on every card and often sell low-cost hardware. Interchange-plus providers pass on the wholesale card fee and add a fixed markup.
| Provider | Hardware prices | In-person rate | Online or keyed-in rate |
|---|---|---|---|
| Square | Reader $59 (first magstripe reader free), Terminal $299, Register $899 | 2.6% + 15¢ (Free plan) | Online 2.9%–3.3% + 30¢ |
| Clover | Go $49, Flex $749, Mini $849, Station Duo $1,899. Software plans from $14.95 per month. | About 2.3%–2.6% + 10¢, depending on plan | About 3.5% + 10¢ |
| PayPal Point of Sale (formerly Zettle) | Reader $29 for the first, $79 each after. Terminal $199. | 2.29% + 9¢ | Keyed-in 3.49% + 9¢ |
| Helcim | Card Reader $199, Smart Terminal $349. No monthly fee. | Interchange + 0.40% + 8¢ (up to $50,000 per month) | Interchange + 0.50% + 25¢ |
Rates change often. Confirm them on each provider's pricing page.
At $50,000 a month in card sales, each percentage point of fees costs $500 a month, or $6,000 a year. Flat-rate pricing is simple but gets expensive as volume grows, so check what you pay now with the calculator below.
Find out how much you’re spending
Calculate your total processing fees
Your total processing fees:
Estimate only. Use the rates on your processing statement for the most accurate result.
The Card Network Settlement and 2027 Fees
Visa and Mastercard have proposed a settlement with merchants that would lower some credit card fees. A federal judge gave preliminary approval on June 9, 2026, and a final approval hearing is set for November 16, 2026. Nothing changes on your statement until the court gives final approval, and merchant groups have said they will appeal.
If approved, the deal cuts the average credit card interchange rate by 0.10 percentage points for five years, caps standard consumer card rates at 1.25%, and lets merchants decline some premium cards. On $50,000 in credit card sales, the cut is worth about $50 a month. Stores on interchange-plus pricing see the savings automatically, while flat-rate processors may keep the difference.
Credit Card Processing Fees and Other Charges
Per-sale fees depend on the card, the risk, and how the card is entered. Debit cards with a PIN cost less, and card-not-present sales cost more.
| Fee | Typical cost | What to ask |
|---|---|---|
| Monthly statement fee | $5–$15 per month | Whether it can be removed |
| PCI compliance fee | $60–$150 per year, or a $10–$30 monthly penalty if you skip the questionnaire | What it covers and when it is billed |
| Chargeback fee | $15–$100 per dispute | The amount for your account |
| Early termination fee | Up to $500 or more | Whether it applies to the lease as well |
| Batch fee | Varies by processor | Whether you can avoid it |
| Software or gateway fee | Varies by processor | What the fee pays for |
Ask your processor which of these charges apply and when, and get the answers in writing.
Buying vs. Leasing a Credit Card Machine
Buy your machine if you can. Marcus signs a 48-month lease at $45 a month for a $300 terminal and pays $2,160, more than seven times its price. Most leases are non-cancelable and run 36 to 48 months.
| Option | Pros | Cons |
|---|---|---|
| Buy |
|
|
| Lease |
|
|
| Rent month to month |
|
|
Typical lease payments run $25–$70 per month.
If you cannot buy, ask about a month-to-month rental, which you can cancel at any time. Be careful with “free” terminals, since their cost is usually built into higher processing rates or monthly fees.
Credit Card Machine Models and Prices
These four terminals are common picks for small retail, and the prices are for new units from resellers. Terminals must be programmed for your processor, and some models do not work with every processor, so confirm compatibility before you buy. Buying through your processor or POS provider avoids reprogramming and wasted time.
| Model | Price (new) | Key features | Best for |
|---|---|---|---|
| Dejavoo QD4 | $280–$380 | Android, touchscreen, built-in printer, Wi-Fi, Ethernet, Bluetooth, NFC, EMV | Small to medium retail |
| Dejavoo Z11 | $180–$340 | 3.5-inch touchscreen, signature capture, Wi-Fi, Ethernet, NFC, EMV | Retail with moderate volume |
| PAX A80 | $270–$430 | 4-inch touchscreen, Android, built-in printer, Wi-Fi, Ethernet, NFC, EMV, optional battery | Small to medium businesses, some mobile use |
| PAX S300 | $150–$300 | Compact PIN pad, color screen, Ethernet and USB, NFC, EMV | Small retail on a budget |
Reseller prices vary. Ask whether the price includes programming for your processor.
Advertised prices can leave out cables, encryption, and programming, which some sellers charge for separately. Ask what the price includes.
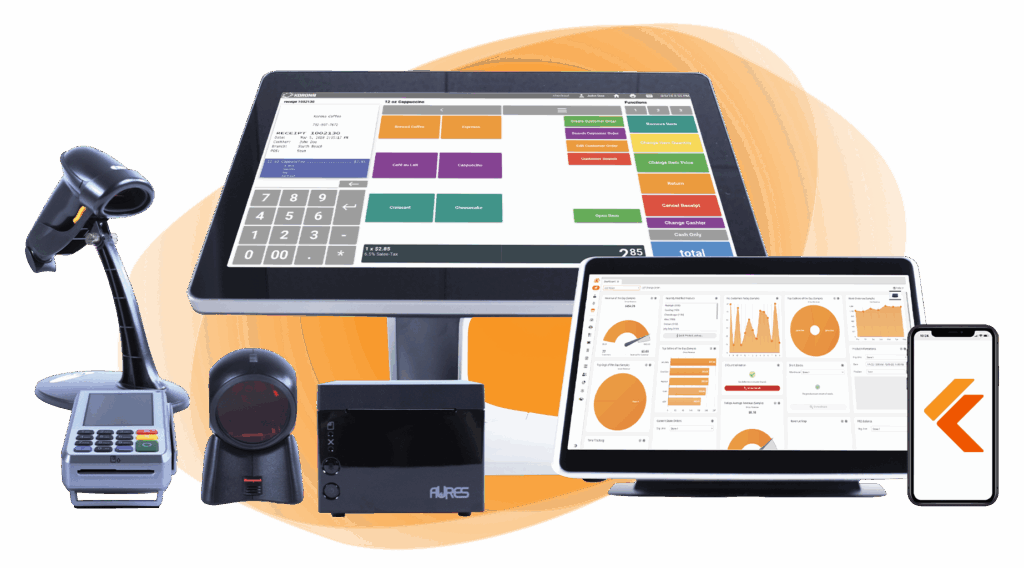
Build Your Own POS
Whether you run a retail store, café, or admissions booth, we have the point of sale hardware designed for your specific needs. Start building your ideal POS system now.
Features to Look for in a Credit Card Machine
Every machine must meet PCI DSS standards, which protect card data from fraud and breaches. Card brands require compliance, and failing to comply can lead to penalties. EMV chip readers create a unique code for each transaction, which helps prevent fraud.
Buy a machine with contactless (NFC) support, since mobile payments like Apple Pay and Google Pay keep growing. NFC lets customers tap a phone or card for a fast, touch-free checkout.
How to Choose a Credit Card Machine
Start with your processor, then pick the machine. Compare processors on rates, contract terms, and support, then choose hardware that works with them and with your POS system.
High-volume stores usually do better buying a machine and negotiating rates, while startups can rent month to month. Make sure the machine supports EMV, contactless, and mobile payments so you do not have to replace it soon.
Speak with a product specialist and learn how KORONA POS can power your business.
Final Thoughts on Credit Card Machine Costs
The machine is a small part of what you pay, so compare processing fees first. KORONA POS can explain your hardware options and show you what you pay for processing.
Get started with KORONA POS today!
Explore all the features that KORONA POS has to offer with an unlimited trial. There’s no commitment or credit card required.
Credit Card Machine Cost FAQs
Can I add a surcharge to card payments?
Visa allows surcharging credit cards in most US states but not debit or prepaid cards. The surcharge can’t exceed your actual acceptance cost or 3%, whichever is lower, and you must give your processor and the card brands 30 days’ written notice. Connecticut and Massachusetts prohibit or heavily restrict credit card surcharges. I named only those two, because sources disagree on which other states ban surcharging. Some rules also vary by state. If you have a blog post on surcharging or cash discounts, link it from this answer.
How fast do I get paid after a card sale?
Square’s standard payout is the next business day, with instant payout available for a 1.75% fee. Clover’s Rapid Deposit has the same 1.75% fee and delivers funds within minutes. I wrote “many processors” for next-day deposits, because I only confirmed it for Square. The weekend and holiday delay line is general knowledge, not from a source.
Can I take card payments with only my phone?
Tap to Pay works on an iPhone XS or newer or an NFC Android phone, through a payment provider’s app. It accepts contactless payments only, not cards that must be inserted or swiped, so a backup reader is a good idea. Square and PayPal don’t charge an extra fee on Tap to Pay payments. Stripe adds 10¢ per authorization, so I kept the rate claim to Square and PayPal.